Section 1250 Recapture
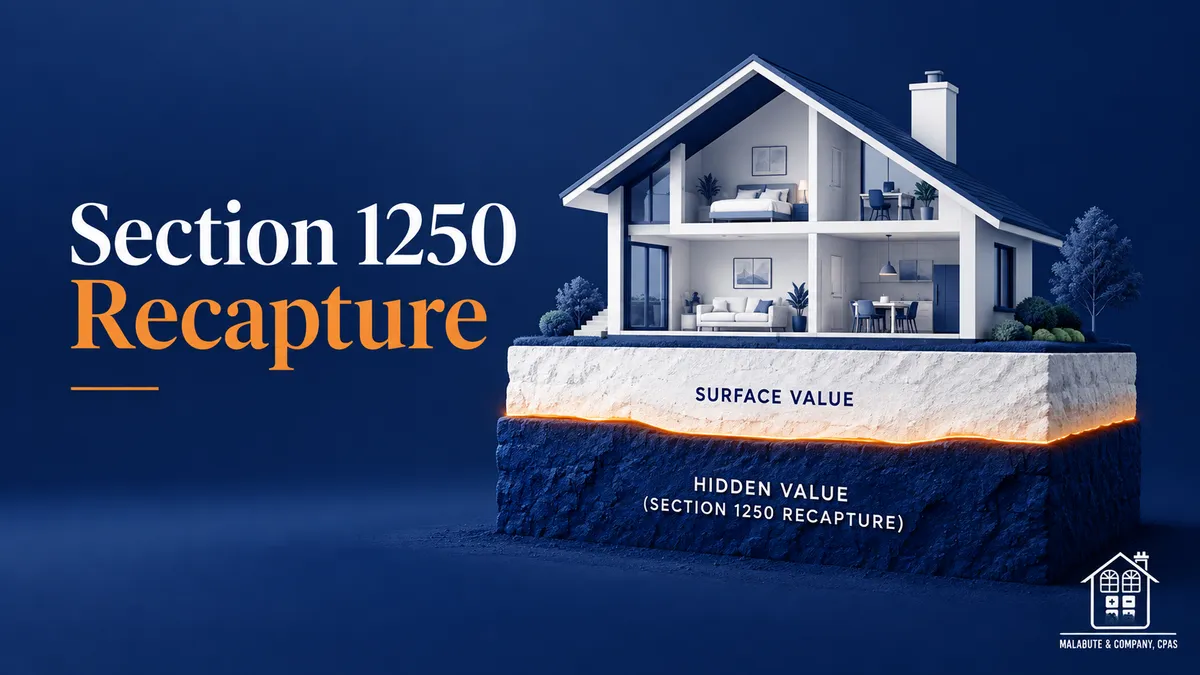
A rental sale can create a bigger tax bill than many investors expect. It's easy to assume that all of your profit will receive the normal long-term capital gains rate of around 20%. But depreciation creates a separate layer. The part of your gain tied to depreciation previously taken on the building is generally unrecaptured Section 1250 gain, which can be taxed at up to 25%. The remaining appreciation receives the normal long-term capital gain treatment.
For example, say you buy a single-family rental for $500,000 and allocate $400,000 to the building and $100,000 to the land. After holding it for 10 years, you've taken roughly $145,000 of straight-line depreciation. If you then sell for $600,000, your adjusted basis is $355,000 and your total gain is $245,000. About $145,000 of that gain falls into the depreciation layer and can be taxed at up to 25% rather than 20%. That difference alone could mean roughly $7,250 more in tax than you expected.
Simply choosing not to take depreciation generally doesn't solve the problem, because depreciation can still come back into the calculation even if you didn't actually claim it. Cost segregation can also affect the exit. It accelerates deductions while you own the property, but personal-property components can be recaptured at ordinary income rates when you sell. That doesn't mean cost segregation is a bad strategy. It means the eventual sale should be modeled when you're deciding whether to do the study.
There are also situations where the result changes. Selling at a loss means there is no recapture. A 1031 exchange postpones the tax rather than eliminating it. If you hold the property until death and your heirs receive a basis step-up, this issue generally disappears for them. Your original land-versus-building allocation matters too, because it affects both the depreciation you receive and what can come back when you sell, so that allocation should be supported when you purchase the property.
Before signing a sale agreement, model what you'll actually have left after taxes. If you plan your next investment assuming a flat 20% tax on the gain, you may discover that the cash you expected to have available simply isn't there.